


Written by: Aaron Rovner, Founder, Saas Hero
Key Takeaways
- CAC payback benchmarks for SaaS vary by ACV, go-to-market motion, gross margin, and net revenue retention. There is no single median that fits every company.
- Under 12 months is strong for B2B SaaS. Mid-market typically runs 14–18 months, and enterprise often runs 18–24+ months when paired with high NDR.
- Always calculate payback using gross margin in the denominator. Revenue-only figures systematically understate the true recovery period.
- Payback and NDR belong together. A long payback is defensible only when NDR exceeds 110% and contracts are sticky and expandable.
- SaaSHero helps B2B SaaS companies point paid acquisition at qualified pipeline and closed revenue so CAC payback becomes a defensible board metric instead of a fragile spreadsheet number.
What Counts As A Good CAC Payback Period?
Under 12 months is strong for B2B SaaS. For mid-market companies at $15K–$100K ACV, typical CAC payback is 14–18 months, and sales-assisted motions generally run 12–18 months. Over 24 months is a risk signal unless ACVs are high, contracts run two to three years, gross retention is roughly 92–96%, and net revenue retention sits comfortably above 115–120%. That combination is the decision rule.
The median has drifted upward in recent years. The 2026 Aleph × Benchmarkit report puts the median B2B SaaS CAC payback at 16 months, down from 18 months in 2024, which is the largest single-year improvement in four years of the dataset. Foundry CRO’s 2026 benchmarks report that mid-market SaaS at $5M–$25M ARR ran a 15-month median in 2023, rising to 18 months in 2026. Rising channel costs, tighter privacy targeting, and AI-driven auction dynamics drive that shift. Treat any pre-2025 median as a historical reference point rather than a current target.
The benchmark only carries weight alongside NDR, gross margin, and ACV. The rest of this article walks through each of those dimensions.
See How You Compare To Benchmarks
CAC Payback Formula Used By Investors
The gross-margin-corrected formula is the standard used by institutional investors such as Bessemer and OpenView. Revenue-based payback is typically discarded in diligence. Comparability still requires matching methodology:
CAC Payback (months) = CAC ÷ (Monthly Recurring Revenue per Customer × Gross Margin %)
ChartMogul’s SaaS metrics library states that gross margin belongs in the denominator because it represents the cash actually available to pay back CAC. Hosting, support, and payment processing costs come out of each customer’s bill before any of it can recover acquisition spend. A revenue-based payback figure ignores those costs and produces a number that is systematically optimistic. At 55–65% gross margin, common for businesses with heavy implementation or professional-services costs, the naive revenue-based payback figure can understate real payback by 40% or more.
Fully loaded CAC must include media spend, agency or team cost, sales salaries and commissions, SDR and BDR headcount, and tooling attributable to acquisition. Fiscallion estimates that 70%+ of founder-built CAC payback calculations use blended gross margin instead of subscription-only gross margin, which artificially shortens reported payback. In one documented case, a company reporting a 12-month payback corrected to 16.5 months once implementation fees carrying roughly 30% margin were stripped out.
Get Help Cleaning Up Your CAC Math
CAC Payback Benchmarks By ACV And Motion
Payback lengthens as ACV rises. Enterprise deals carry longer sales cycles, larger buying committees, solution engineers, security reviews, and procurement processes. All of that lands in acquisition cost before any revenue arrives. Self-serve motions spend less per customer and collect sooner. The table below reflects this structural pattern.
| ACV Band | GTM Motion | Typical Payback | How To Read This Benchmark |
|---|---|---|---|
| Under $15K | Self-serve / PLG | 8–12 months | Shortest payback is structural. Low ACV and low NDR mean the cash must come back fast. |
| $15K–$100K | Sales-led mid-market | 14–18 months | The middle band is the modern default. Anything above 20 months here needs an NDR justification. |
| Above $100K | Enterprise sales-led | 18–24+ months | A long payback is defensible only when the contract is large, sticky, and expandable. |
These ranges are consistent across the Optifai Sales Ops Benchmark covering 939 B2B SaaS companies on Q2 2025–Q1 2026 data, Bessemer Venture Partners’ ACV-band targets from their “Scaling to $100 Million” framework, and High Alpha’s 2024 SaaS benchmarks.
A 20-month enterprise payback can be structurally healthier than a 12-month SMB payback. The enterprise contract is larger, stickier, and more expandable. Enterprise SaaS with 130% NRR can justify an 18–24 month payback because customer revenue grows 30% annually through expansion. SMB at 105% NRR lacks that compensation and must target under 12 months. Without the NDR context, the benchmark is just a number.
How Gross Margin Changes Your CAC Payback
Two companies with identical CAC and MRR can have materially different payback once gross margin is applied. Consider a company with $10,000 CAC and $833 new MRR per customer. At 76% gross margin, the gross-margin-adjusted payback is 15.8 months. On a revenue-only basis, the same company reports 12.0 months, a 3.8-month difference that moves the business from looking efficient to sitting at the upper boundary for mid-market.
The correction is straightforward. Any payback figure calculated on revenue rather than gross margin is optimistic, and comparisons across companies are only valid when both use the same basis. At 80% gross margin, adjusting for margin extends the payback period by 25%. At 55% gross margin, the adjustment extends payback by more than 80%. A low-gross-margin SaaS business needs a shorter payback to compensate because the denominator is smaller and the recovery takes longer.
The Payback-Plus-NDR Interpretation Matrix
Payback measures how fast cash comes back. NDR measures whether the customer base compounds. Read together, they produce a clear judgment. Read separately, they produce a number with no context. The matrix below maps each payback band against three NDR ranges so you can locate your own combination and see whether it signals strength, norm, or risk.
| CAC Payback | NDR Below 100% | NDR 100–110% | NDR Above 110% |
|---|---|---|---|
| Under 12 months | Strength, because fast cash return offsets a shrinking base. | Strength, because the business is efficient and stable. | Best-in-class, because the business is efficient and compounding. |
| 12–24 months | Risk, because customers churn before payback completes. | Norm, which is acceptable if the trend is improving. | Defensible, because expansion funds the wait. |
| Over 24 months | Critical risk, which is unsustainable without immediate correction. | Watch item that needs a clear path to NDR above 110%. | Defensible growth investment, but only with multi-year contracts and high gross margin. |
Kyle Poyar’s rule of thumb, drawn from the 2025 SaaS Benchmarks Report covering 660 private SaaS companies, sets CAC payback targets by NRR band: below 100% NRR, target under 12 months; 100%–120% NRR makes 12–18 months defensible; above 150% NRR makes longer payback survivable depending on cash reserves. The NDR medians by segment reinforce the matrix. The Optifai benchmark reports median NDR of 97% for SMB, 108% for mid-market, and 118% for enterprise. Enterprise carries both the longest payback and the highest retention, while SMB carries the shortest payback and the lowest retention.
A 20-month payback with NDR above 110% is a defensible growth investment. The same 20-month payback with NDR below 100% is a cash trap. Customers churn before the acquisition cost is recovered, and the company funds the gap with capital rather than with customer revenue.
CAC Payback Vs. LTV:CAC Ratio
LTV:CAC measures whether a customer is worth acquiring over their lifetime. The commonly cited healthy threshold for SaaS is 3:1. CAC payback measures how long the acquisition cost is tied up before cash comes back. A company can pass one test while failing the other.
A strong LTV:CAC can mask a dangerous payback. A 5:1 ratio with a 30-month payback means excellent lifetime returns and a brutal wait. Every increment of growth demands outside capital because recovered cash arrives too slowly to reinvest. A business with a six-month CAC payback recycles the same sales and marketing dollar roughly twice a year. A business with a 24-month payback recycles it once every two years, which forces growth to be funded by investors or lenders rather than by customers already won.
A fast payback can mask a weak LTV:CAC. High churn means customers pay back their acquisition cost quickly and then leave, which produces a short payback and a thin lifetime return. Both metrics belong on the board deck. Neither replaces the other.
CAC Payback Vs. Discounted Payback And IRR
CAC payback is a simple, undiscounted marketing efficiency metric. It answers one question: how many months of gross margin does it take to recover acquisition cost? It does not discount future cash flows and does not account for the time value of money.
Discounted payback and IRR are capital-budgeting concepts used to evaluate investments where the cost of capital is material to the decision. Finance teams typically use them in models for major infrastructure or M&A decisions. Bessemer documents an 8% valuation discount per additional month of CAC payback beyond a company’s cost-of-capital threshold. The cost of capital sets the ceiling on tolerable payback, but the operating metric used to manage the go-to-market team is the undiscounted version.
For go-to-market teams, CAC payback remains the practical operating metric. It is fast to calculate, easy to segment by channel and cohort, and directly actionable. Finance teams may layer discounted payback or IRR into capital allocation models, but those sit as board-level inputs rather than campaign-level levers.
Review Your CAC Payback With An Expert
How To Improve CAC Payback Without Slashing Acquisition
Improvement requires working several levers at once. Cutting acquisition spend can shorten payback on paper while starving the pipeline the company needs next quarter.
- Expansion Revenue And Pricing. Raising NDR improves the interpretation of an unchanged payback. Improving net revenue retention from 100% to 120% shortens effective payback by 2–4 months, with each 5 percentage points of NRR adding roughly 1 month of payback compression. A 10–15% price increase on new logos shortens payback proportionally without touching CAC.
- Sales-Cycle Compression. A shorter cycle pulls cash back sooner and reduces the fully loaded cost of a deal. Each additional week in the average sales cycle increases the fully loaded cost to close.
- Lead-Quality Improvement. Most B2B companies generate two to three times more leads than they can effectively work. Reducing lead volume while increasing quality is one of the fastest paths to a shorter CAC payback period.
- Gross-Margin Improvement. Improving gross margin from 72% to 78% shortens CAC payback by 4.3 months at typical SaaS unit economics.
- Channel-Mix Efficiency. Reallocating budget toward channels that produce qualified pipeline rather than raw form fills changes the effective CAC. Most companies find 20–30% of their acquisition budget goes to channels with CAC 2–3x higher than their best channels. Reallocating that spend improves blended payback immediately.
Identify Your Fastest Payback Levers
Where SaaSHero Fits In Your CAC Payback Strategy
The levers above all assume the acquisition engine is pointed at the right outcome. In practice, the CAC payback number is a function of what the paid acquisition engine is optimized toward. Most agencies optimize toward form fills. An algorithm rewarded for form fills finds the people most likely to fill in forms: students, competitors, job seekers, existing customers. It reports a falling cost per conversion while pipeline stays flat. The payback number in the spreadsheet reflects that optimization, whether or not anyone has named it.
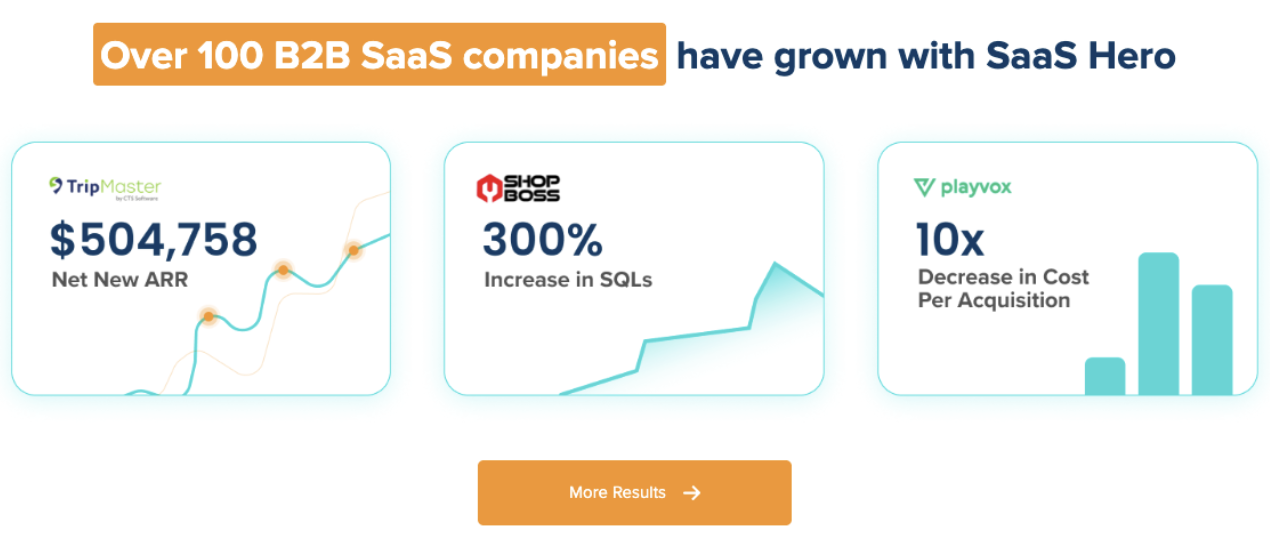
SaaSHero is the outsourced inbound growth team for B2B SaaS, founded in 2018, with more than 100 B2B companies served and over $60M in lifetime ad spend managed. The firm optimizes against CRM outcomes such as qualified pipeline, lifecycle stage, and closed revenue rather than the conversion counts the ad platforms report. That focus makes CAC payback a number the marketing leader can actually defend because the acquisition engine is pointed at the right signal from the start.
SaaSHero owns paid media, creative, landing pages and CRO, attribution and reporting, and strategy as one team. The post-click experience and the measurement layer stay under one roof instead of being handed back to the client. The benchmarks SaaSHero holds accounts to, LTV:CAC of 3:1 and CAC payback under 12 months, are the standards it manages toward rather than aspirations it reports against.
A marketing leader with a board meeting coming and a payback number that needs defending must know whether the acquisition engine is optimized toward the right outcome. If the answer is form fills, the payback number will reflect that. If the answer is qualified pipeline and closed revenue, the payback number becomes defensible.
Align Paid Acquisition With Defensible Payback
Conclusion And Next Steps
CAC payback benchmarks for SaaS only make sense when segmented by ACV, go-to-market motion, gross margin, and NDR. A 20-month payback in the enterprise band with 118% NDR and 80% gross margin is a different story from a 20-month payback in the mid-market band with 101% NDR and 72% gross margin. Those situations call for different interpretations and different action plans.
The practical next steps are clear. Recalculate payback on a gross-margin basis if the current figure uses revenue. Check NDR alongside it and locate the combination in the matrix above. Then audit whether the paid acquisition engine is optimized toward qualified pipeline or form fills, because the payback number reflects that optimization. Changing the optimization is often the fastest path to a number that holds up in a board conversation.
Audit Your CAC Payback With SaaSHero