Written by: Aaron Rovner, Founder, Saas Hero | Last updated: August 31, 2026
Key Takeaways
CAC payback period shows how many months of gross profit it takes to recover acquisition cost. Use CAC ÷ (Monthly ARPA × Gross Margin %).
B2B SaaS payback is harder to calculate than B2C because long sales cycles, annual contracts, and variable gross margins complicate the model.
Accurate inputs matter: fully-loaded CAC, subscription gross margin, and segment-specific ARPA prevent the 25–60% misstatements common across the industry.
Benchmarks vary by segment: under 12 months for SMB, 12–18 months for mid-market, and 18–36 months for enterprise, so track payback by segment.
SaaSHero connects paid campaigns to CRM pipeline and revenue data so ad platforms optimize for qualified opportunities, which shortens payback. Book a discovery call with SaaSHero to see how.
Why CAC Payback Period Is Tricky in B2B SaaS
CAC payback period looks simple on paper but becomes complex in real B2B SaaS environments. Long sales cycles, annual contracts, and changing gross margins all affect the math and can distort the result.
This guide speaks to founders, CFOs, VPs of Marketing, and finance analysts at B2B SaaS companies with $10M+ revenue. Use it when you need a defensible payback number for internal analysis, investor updates, or board decks.
Here is what you will find in this article:
The exact formula and a step-by-step walkthrough
Benchmarks by customer segment
Adjustments for annual contracts
Ways to improve payback using CRM-connected acquisition
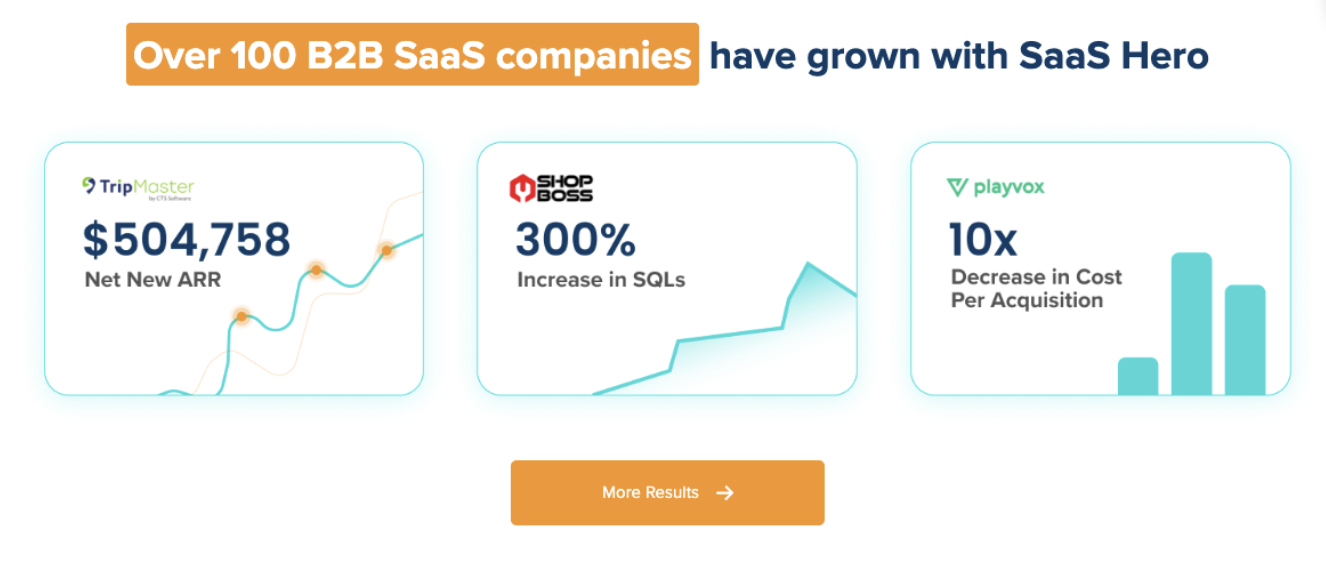
Over 100 B2B SaaS companies have grown with saas here
Data You Need Before You Run the CAC Payback Formula
Gather these four inputs before you calculate CAC payback:
CAC (Customer Acquisition Cost): Total sales and marketing expenses divided by new customers acquired in a period. Include fully-loaded headcount, ad spend, tools, agency fees, and commissions, not just media spend.
Monthly ARPA (Average Revenue Per Account): Average monthly recurring revenue from new customers acquired in the measurement period. Use new-logo ARPA, because total book ARPA blends older, cheaper cohorts and makes payback look longer.
Contract Length: Monthly, annual, or multi-year billing terms, which change how quickly cash returns.
Watch for these common pitfalls before you start:
Using revenue instead of gross profit in the denominator
Leaving out sales headcount, SDR, and BDR costs from CAC
Ignoring contract length when you interpret the result
The 4-Step Framework for CAC Payback Period
Use this simple framework to calculate CAC payback correctly:
Calculate CAC using total sales and marketing spend divided by new customers acquired.
Determine gross margin so you know the profit available to repay acquisition costs.
Apply the formula CAC ÷ (Monthly ARPA × Gross Margin %).
Interpret the result against segment-specific benchmarks.
Step 1: Calculate CAC With Fully-Loaded Costs
CAC is the input most teams miscalculate. The correct version includes all sales and marketing expenses, not just ad spend.
Formula: CAC = Total Sales & Marketing Expenses ÷ New Customers Acquired
Example: If you spend $100,000 on sales and marketing, including salaries, ad spend, tools, and agency fees, and acquire 20 new customers, CAC equals $5,000.
TripMaster adds $504,758 in Net New ARR in One Year
Step 4: Compare CAC Payback to Segment Benchmarks
After you calculate payback, compare it to segment benchmarks instead of relying on a single blended number. Segment-level analysis reveals which motions actually work.
Use these general thresholds when you interpret your number:
Under 12 months: Strong, you can reinvest aggressively
12–18 months: Typical for many B2B SaaS companies
18–24 months: Concerning, growth requires heavy capital
Over 24 months: Critical, the motion likely has a structural issue
Enterprise companies with ACV over $100K can often support 18–24 months if net revenue retention exceeds 110%, because expansion revenue compounds cohort value.
SaaSHero fixes this by connecting paid campaigns directly to CRM lifecycle data such as qualified pipeline, opportunity creation, and closed revenue. Ad platforms then learn from the right signal, which shifts budget toward better keywords, higher-quality audiences, and stronger opportunities.
SaaSHero helps B2B SaaS teams reduce CAC payback by optimizing campaigns for qualified pipeline and revenue instead of raw leads. Book a discovery call to learn how.
Over 100 B2B SaaS Companies Have Grown With SaaS Hero
Frequently Asked Questions
What is a good CAC payback period for B2B SaaS?
Under 12 months is strong for most B2B SaaS companies. The median across segments sits around 15 months, based on data from 939 B2B SaaS companies between Q2 2025 and Q1 2026. SMB and self-serve companies should target under 12 months, mid-market companies 12–18 months, and enterprise companies 18–36 months. Enterprise companies with ACV over $100K can support longer payback if net revenue retention exceeds 110%, because expansion revenue compounds cohort value. A payback period above 24 months without strong NRR signals a capital efficiency problem that higher acquisition spend will not solve.
How do I calculate CAC payback with annual contracts?
Use annual gross profit divided by 12 to convert to a monthly figure, then apply the standard formula: CAC ÷ (Annual Gross Profit ÷ 12). Focus on the difference between cash payback and GAAP payback. If a customer prepays annually, cash payback may occur in month one because the full year’s revenue arrives at signing. Recognized-revenue payback still spreads across the contract term under ASC 606. If annual prepay exceeds 30% of new bookings, report both figures to your board. Relying on one number misleads capital planning. Moving customers to annual prepay improves cash payback quickly, but reflects a collections shift rather than a true efficiency gain.
Why does gross margin matter in the CAC payback calculation?
Gross margin reflects the profit available to repay acquisition costs. Revenue-based calculations ignore the cost of delivering the product and make payback look 25–40% shorter than reality. For B2B SaaS, COGS usually includes hosting and infrastructure, customer support headcount, third-party API fees, and onboarding costs. Use subscription gross margin, not blended gross margin that includes lower-margin services. Blended gross margin inflates the denominator and shortens payback on paper. Typical B2B SaaS subscription gross margin runs 70–80%. Running the calculation at 100% margin overstates efficiency by roughly 25–40%.
How often should I recalculate CAC payback?
Recalculate monthly if you spend heavily on acquisition, or quarterly if you are smaller. Annual views hide quarterly swings that reveal deeper unit economics issues. Track payback by cohort, by acquisition channel, and by customer segment instead of relying on a single blended number. A blended payback of 14 months can hide paid search at 28 months and referrals at 3 months, which leads to poor budget allocation. Investors and PE operating partners now expect payback by channel and segment vintage, not just a headline metric. Worsening payback across cohorts is the signal that matters most for fundraising and budget discussions.
What is the relationship between CAC payback period and LTV:CAC?
CAC payback and LTV:CAC measure different parts of unit economics. CAC payback shows when cash returns and determines how quickly you can recycle acquisition capital. LTV:CAC shows how much value returns over the customer lifetime. A healthy LTV:CAC of 3:1 or higher confirms that each customer generates more value than their acquisition cost, but it does not guarantee the company will stay solvent long enough to realize that value. A company with a 5:1 LTV:CAC and a 36-month payback can still face serious cash pressure if growth is fast and NRR sits below 100%. Most boards look for payback under 18 months, LTV:CAC above 3:1, and NRR above 110%.
Conclusion: Get CAC Payback Right, Then Make It Better
Accurate CAC payback requires four steps. Calculate CAC with fully-loaded costs, determine subscription gross margin, apply the formula, and compare the result to segment-specific benchmarks instead of a single industry average.
Use this quick checklist:
Calculate your current payback using gross margin, not revenue
Compare your number to benchmarks for your specific segment
Identify segments and channels with the longest payback
Check whether paid acquisition optimizes against CRM data or only form fills
The formula is only as strong as its inputs. When ad platforms train on form submissions instead of qualified pipeline, CAC rises and payback stretches. SaaSHero’s outsourced growth team fixes the data quality problem by connecting paid campaigns to CRM lifecycle events, so optimization follows the outcomes that matter to your board. Book a discovery call with SaaSHero today.
Includes unlimited revisions as well as custom written copy (from a human, not ChatGPT). We’ll send a first draft in Figma and you can request as many edits as you’d like. We won’t ever activate any landing pages until you give us the final OK