


Written by: Aaron Rovner, Founder, Saas Hero
Key Takeaways
- Enterprise SaaS CAC payback typically runs 18–24 months for ACV above $100K. Long sales cycles, multi-stakeholder committees, and implementation costs drive this range.
- Fully loaded CAC must include sales engineering, onboarding, tools, and allocated overhead. Marketing-only CAC often understates the true cost by 2–3x and misleads board or PE reviews.
- Using ACV and monthly gross profit in the payback formula prevents the 2–3x distortion that appears when teams use TCV or top-line revenue.
- Strong NRR (118%+ median for enterprise) and annual prepayment make longer paybacks defensible by accelerating cash recovery and improving cohort economics.
- SaaSHero ties paid acquisition to CRM revenue data so the fully loaded CAC in the payback formula reflects actual spend instead of inflated form-fill metrics.
See How SaaSHero Measures CAC Payback In Your CRM
Definition Of CAC Payback For Large Enterprise SaaS
The CAC payback period for large enterprise SaaS is the number of months required to recover fully loaded CAC divided by monthly gross profit from a new customer. Enterprise SaaS benchmarks from Bessemer Atlas, OpenView Partners, and SaaStr aggregate reporting place this range at 18 to 24 months for ACV above $100K. Long sales cycles, multi-stakeholder buying committees, procurement and security review, and implementation costs that do not appear in SMB deals drive this outcome.
How To Calculate CAC Payback For Enterprise SaaS
The formula is:
CAC Payback Period (months) = Fully Loaded CAC ÷ (Monthly Revenue Per Customer × SaaS Gross Margin %)
Each term in that formula behaves differently in an enterprise motion.
Fully loaded CAC for a $100K+ ACV deal includes all of the following, per Gangly’s CAC payback glossary:
- Sales rep salaries and commissions prorated to new-logo activity
- Sales engineering time on deals that close and deals that do not
- Implementation and onboarding cost per new customer
- Marketing program spend attributed to the deal
- Sales tools, CRM licenses, and ABM platform costs
- Management overhead allocated to the GTM function
DMW Advisory’s worked example illustrates the gap. A company spends $60K on marketing, $90K on two fully loaded AEs, $5K on tools, and $8K on onboarding support. It closes 20 new customers and produces a fully loaded CAC of $8,150 versus a marketing-only CAC of $3,000. That is a 2.7x undercount, and a CFO or PE operating partner will recompute it during diligence.
Why gross profit is the denominator: CFO Advisors notes that a company with 70% gross margins that skips the margin adjustment understates CAC payback by 43%. Revenue payback and CAC payback are different metrics and should carry different labels.
Worked example using realistic enterprise inputs:
- ACV: $120,000 ($10,000 per month)
- Blended SaaS gross margin: 75%
- Monthly gross profit: $10,000 monthly revenue × 75% gross margin = $7,500
- Fully loaded CAC: $30,000 (calculated as $1,800,000 in total fully loaded S&M spend divided by 60 net new logos)
- CAC payback: $30,000 ÷ $7,500 = 4 months
This example shows how the math flows when every input is defined clearly. Your own numbers will likely sit higher in the enterprise range once you include all costs and use gross profit.
Review Your CAC Inputs With SaaSHero
Why Enterprise CAC Payback Is Longer Than SMB
Enterprise CAC payback runs longer than SMB because the motion itself is heavier, not because the team is necessarily inefficient. Median B2B SaaS CAC by go-to-market motion is $702 for self-serve/PLG versus $11,400 for enterprise sales-led, a 16x gap driven by clear structural factors:
- Sales cycle length: Enterprise cycles run 6 to 18 months. Every month in the pipeline adds AE salary, SE time, and marketing spend before any revenue appears.
- Buying committee size: Multiple stakeholders such as the economic buyer, technical evaluator, procurement, security, and legal each add time and cost to the close.
- Implementation cost: For enterprise sales, onboarding cost per customer can be $10,000 or more and belongs in fully loaded CAC.
- Low-margin services revenue: Implementation and professional services delivered at 20–40% gross margin drag down the blended margin used in the payback denominator.
The SMB benchmark of 6–12 months reflects low ACVs, short sales cycles, and weaker retention (GRR commonly 75–85%). SMB motions that cannot get under 12 months usually have a pricing issue or a motion mismatch. Applying that benchmark to a $150K ACV field-sales deal creates a misleading comparison.
The Multi-Year Contract And Annual-Prepay Question
Those structural drivers explain why enterprise payback runs long. The most common way companies misstate it sits in how they treat multi-year contracts and annual prepayment.
TCV vs. ACV in the formula: A three-year, $300K TCV deal has an ACV of $100K. The payback formula should use ACV, the annualized recurring value. For a three-year contract, using TCV instead of ACV in the denominator makes payback appear three times shorter than it is on a recurring-revenue basis, since a $300,000 three-year deal is $300,000 TCV but only $100,000 ACV.
Cash payback vs. accounting payback: When a customer prepays annually, cash arrives on day one. A $120K annual prepayment against a $180K fully loaded CAC means the company has recovered $120K in cash by month one, while CAC is not recovered on a gross-profit basis until month 24 because revenue is recognized ratably and margin accrues monthly. Annual prepayment puts cash in the bank on day one but does not change the standard CAC payback formula, which uses monthly recurring revenue regardless of how the customer paid.
Board recommendation: Report both views. Cash payback guides runway and burn planning. Accounting payback, gross-margin-adjusted and based on monthly ACV, compares cleanly against published benchmarks and investor expectations. Label each clearly and keep definitions consistent across meetings.
Services And Implementation Margin Drag
Enterprise SaaS companies often bundle professional services and implementation into the initial contract. That revenue is real, yet it carries a very different margin profile. Benchmarkit’s 2025 B2B SaaS Performance Metrics report found a median subscription revenue gross margin of 81% and a professional-services gross margin of only 30%.
When services revenue reaches 15–20% of total revenue, the blended gross margin used in the payback denominator falls well below the subscription-only margin. A company with 80% subscription gross margin and 25% services gross margin could report a 65–68% blended gross margin if services account for 30% of total revenue. That compression mechanically lengthens payback.
The board presentation fix is simple. Report subscription gross margin and services gross margin as separate line items. Present SaaS CAC payback using subscription-only gross margin and note the blended figure alongside it. This keeps high-margin recurring software economics visible instead of burying them under loss-leading implementation revenue.
How Net Revenue Retention Changes Enterprise Payback
A 24-month payback on a customer with 120%+ NRR represents a very different investment than the same payback on a customer at 95% gross retention. Enterprise SaaS (defined as $100K+ ACV) carries a median NRR of 118% and an elite NRR of 130%+. At 120% NRR, the existing customer base grows 20% per year without a single new logo, so every acquisition dollar compounds through expansion.
Expansion revenue should sit in a separate model from initial payback instead of blending into it. Expansion revenue does not count toward standard CAC payback because payback measures new-customer acquisition against new-customer ARR; expansion belongs in net revenue retention instead. Strong expansion explains why enterprise motions receive longer payback allowances. When customers reliably grow 20–30% per year, the true return on acquisition spend exceeds what the initial payback suggests.
In a board conversation, a clear framing sounds like this: “Our 22-month payback is calculated on initial ACV at 75% gross margin. Our NRR of 122% means the cohort economics improve materially in years two and three without incremental acquisition spend.”
Model NRR And Payback With SaaSHero
What Is A Good CAC Payback Period For Enterprise SaaS?
The following four-tier benchmark range is grounded in Bessemer Atlas, OpenView Partners, and SaaStr aggregate reporting, cross-referenced with the 2026 Aleph × Benchmarkit report (342 companies with FY2025 actuals, of which 198 reported the CAC payback metric) and CFO Advisors’ 2026 Series A benchmarks. These are ranges, not universal thresholds. ACV, NRR, gross margin, and capital structure all influence what is defensible. The table below maps each payback band to what it signals about go-to-market health.
| Tier | Payback Range | Assessment |
|---|---|---|
| Best-in-class | Under 18 months | Top-quartile enterprise performance; signal to invest more aggressively |
| Healthy | 18–24 months | Expected range for ACV above $100K with NRR above 110% |
| Acceptable | 24–36 months | Defensible for strategic accounts with strong NRR and capital discipline |
| Concerning | 36+ months | Requires exceptional NRR (130%+) and LTV justification to defend |
Five Factors That Shape Enterprise CAC Payback Quality
Five specific factors determine whether a given payback number is defensible in a board or PE portfolio conversation:
- Net Revenue Retention (NRR): Kyle Poyar’s rule of thumb sets CAC payback targets by NRR band — below 100% NRR targets under 12 months, 100%–120% NRR makes 12–18 months defensible, and above 150% NRR a longer payback is survivable depending on cash reserves. NRR acts as the multiplier on every acquisition dollar.
- ACV: Enterprise SaaS companies with $50K–$100K contract values had a median CAC payback of 22 months, twice as long as the 11 months for sub-$5K contract value companies. The benchmark must match the ACV band.
- Sales cycle length: A 9-month enterprise sales cycle means acquisition costs accrue for three quarters before any revenue appears. Payback starts at close, not at first contact.
- Gross margin: Moving gross margin from 72% to 78% shortens CAC payback by 4.3 months at typical SaaS unit economics. Services margin drag often lengthens payback quietly.
- Cash collection terms: Annual prepayment compresses cash payback relative to accounting payback. On a $120K per year ACV deal billed annually upfront, a SaaS company that recognizes revenue monthly under GAAP can see a roughly 12-month gap between cash payback and accounting payback, since the cash is collected upfront while revenue is recognized over 12 months. Both numbers belong in the board deck.
How To Present CAC Payback To Your Board Or PE Operating Partner
Board conversations about CAC payback work best when you tailor the framing to where the number lands.
18–24 months (healthy): “Our 22-month payback is calculated on fully loaded CAC, including sales engineering, implementation, and allocated marketing spend, divided by monthly gross profit at 75% SaaS margin. That sits in the expected range for our ACV and sales motion. Our NRR of 118% means the cohort pays back faster on an expansion-adjusted basis, and our cash payback is 14 months given annual prepayment.”
24–36 months (defensible with strong NRR and capital discipline): Lead with NRR and LTV. A longer payback is defensible when customer retention is high, expansion revenue is meaningful, and capital is available to fund the acquisition gap without constraining other operations. Name the primary lever you are working: gross margin improvement, ACV increase, or cycle compression.
36+ months (concerning): Treat the number as a diagnosis prompt. Identify whether pricing, services margin, or sales cycle length drives the result. Each driver points to a different fix, and a board or operating partner will ask which one you are addressing first.
Adjacent metrics a CFO or operating partner will ask about alongside payback include:
- LTV:CAC: The long-horizon story. At Series A, CAC payback is more important than LTV:CAC because LTV:CAC depends on a customer lifetime assumption that cannot be credibly estimated with only 18 months of cohort data. Present both and label the assumptions in LTV.
- Rule of 40: Only 11% to 30% of private SaaS companies currently exceed a Rule of 40 score of 40. A long payback paired with a strong Rule of 40 score changes the conversation.
- Pipeline coverage: A 3–4x coverage ratio tells the board whether the payback number will likely improve next quarter or worsen.
Where SaaSHero Fits In Your CAC Payback Strategy
The measurement problem behind a long CAC payback often starts upstream of the calculation itself. An ad platform optimized toward form fills finds the cheapest people to fill out forms, such as students, competitors, and job seekers, instead of the people who buy $100K+ ACV contracts. That pattern inflates CAC and lengthens payback before anyone touches a spreadsheet.
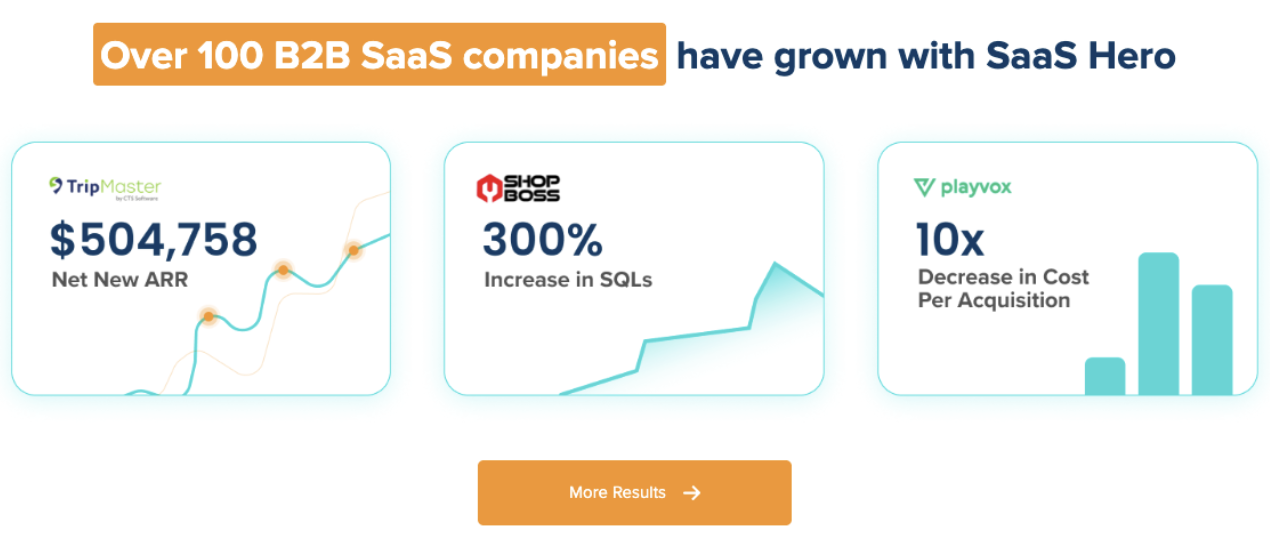
SaaSHero is the outsourced inbound growth team for B2B SaaS companies that optimizes paid acquisition against CRM revenue data such as qualified pipeline, lifecycle stage, and closed revenue rather than form-fill counts. That distinction matters because the ad platforms only know what you send them. If you send form fills, they find more form fills.
SaaSHero separates primary from secondary conversions and pushes lifecycle stage events back into the ad platforms so the algorithms optimize toward buyers. Because the retainer is indexed to total monthly ad spend rather than channel count, you can shift budget toward whichever channel produces qualified pipeline without paying a fee to do so.
SaaSHero also owns landing pages, creative, and reporting as one team. The entire chain from impression to CRM record stays accountable, which makes the fully loaded CAC entering the payback formula far more defensible.
See How SaaSHero Improves CAC Payback Quality
Frequently Asked Questions
What Is A Good CAC Payback Period For Enterprise SaaS?
For enterprise SaaS with ACV above $100K, the healthy range of 18 to 24 months appears earlier in this guide. Under 18 months is best-in-class. A 24–36 month gross-margin-adjusted CAC payback is acceptable for early-stage or up-market motions, particularly when NRR exceeds 110% and gross retention is strong. A CAC payback period above 36 months is described as “distressed” and only works with extraordinary retention, specifically requiring net revenue retention above 120% and an LTV:CAC ratio above 4:1, according to Optifai’s 2026 B2B SaaS dataset (n=939). The benchmark must always match the ACV band and sales motion.
How Is CAC Payback Different From LTV:CAC?
CAC payback is a cash-flow metric that measures how many months of gross profit are required to recover acquisition spend. LTV:CAC is a profitability ratio that measures total return across the customer’s lifetime relative to what was spent to acquire them. A business can show a strong LTV:CAC ratio and still have a long payback, which is common in enterprise SaaS where customers are valuable but monetize slowly over multi-year contracts. For board and PE conversations, payback usually serves as the more defensible near-term metric because it uses only observed numbers. LTV:CAC depends on a churn assumption that may not be validated for 18 to 24 months of cohort data.
Does Annual Prepayment Change CAC Payback?
Annual prepayment changes cash payback but not accounting payback. When a customer prepays a $120K annual contract on day one, cash arrives immediately, while revenue is recognized ratably over 12 months and gross margin accrues monthly. The standard CAC payback formula still uses monthly recurring revenue regardless of payment timing, so accounting payback remains the same. Cash payback, however, can collapse by roughly 8 to 11 months on an annual prepay deal compared with monthly billing, since the full acquisition cost is recovered in the first month rather than spread across the year. Both numbers matter: cash payback governs runway and burn planning, and accounting payback compares cleanly against published benchmarks.
How Does NRR Affect CAC Payback?
NRR does not change the initial CAC payback calculation, which is measured on new-customer ARR at the time of acquisition. NRR changes how defensible that number looks. At 120%+ NRR, the cohort economics improve materially in years two and three without incremental acquisition spend, so the true return on acquisition investment exceeds what the initial payback implies. Enterprise SaaS with ACV above $100K carries a median NRR of 118%, which explains why a 24-month payback can be acceptable in that segment while the same number would raise concerns in SMB. In a board conversation, NRR provides the context that turns a long payback into a strategic choice instead of a go-to-market problem.
Conclusion
Enterprise CAC payback runs structurally longer than SMB benchmarks suggest, and the number becomes defensible when you calculate and present it correctly. Fully loaded CAC divided by monthly gross profit produces a number a CFO or PE operating partner can evaluate against the right benchmark. Revenue, TCV, or blended margin that includes low-margin services will distort the picture.
The operational fix for a payback number that runs longer than it should usually sits upstream. Conversion events feeding the ad platforms, margin drag from services revenue, and attribution models that credit the wrong channels all shape the final figure. SaaSHero acts as the outsourced inbound growth team that aligns paid acquisition with CRM revenue data, keeps the measurement chain from impression to closed revenue accountable, and makes the fully loaded CAC in the payback formula reflect what the business actually spent to win the customer.
Talk With SaaSHero About Your CAC Payback