


Written by: Aaron Rovner, Founder, Saas Hero
Key Takeaways
- CAC payback period reporting for investors must be gross-profit-adjusted, cohort-segmented, and paired with a written narrative to withstand investor scrutiny.
- Revenue-based payback overstates efficiency by 15–25% and fails investor verification checks, while gross-profit-adjusted payback reports true cash recovery.
- Investors expect a structured quarterly comparison table with specific rows for payback period, CAC definition, cohort view, and churn context instead of a single blended number.
- Present blended and paid CAC side by side, with cohort and segment breakdowns, so investors can see channel efficiency and segment-level performance clearly.
- SaaSHero provides CRM-connected measurement and reporting that focuses on revenue outcomes, enabling the gross-profit-adjusted, cohort-level CAC payback reporting investors expect.
See How SaaSHero Reports CAC Payback
Why Your CAC Payback Number Gets Challenged
Three weeks before a board meeting, most $10M–$50M B2B SaaS companies rely on a CAC payback number built on revenue-based payback, blended across channels, and presented as a single point-in-time figure. An investor asks how it was calculated. The explanation often fails basic verification.
The number matters because it tells investors whether growth is self-funding. Falcon Capital Partners defines CAC payback as the number of months it takes a company to recoup its investment in a new customer from the gross profit that customer generates, not from revenue alone. For PE sponsors operating within a four-to-seven year hold period, payback beyond 18 months means new customer investments in the first two years of ownership may not produce meaningful returns before the planned exit.
The credibility problem is structural. Fairview’s May 2026 CAC payback guide states that investors reviewing CAC payback in a data room verify six things: gross-margin adjustment, CAC definition consistency, cohort-level validation by channel and segment, churn against payback, trend direction, and Magic Number alignment. A revenue-based figure fails the first check before the conversation begins.
Why CAC Payback Reporting Breaks Down In B2B SaaS
The reported number is often indefensible because B2B SaaS acquisition does not fit a single-period calculation. Sales cycles run for months, buying committees make decisions, and journeys span ad platforms, CRM, and marketing automation. Spend and revenue land in different reporting periods, so a simple snapshot hides the real economics.
Revenue-based payback overstates go-to-market efficiency by 15–25% in a typical SaaS business because it treats all revenue as available to repay acquisition cost, while only gross profit is. Gross margins of 55–65% are common for businesses with heavy implementation, hosting, or professional-services costs. At those margins, the naive revenue payback figure can understate real payback by 40% or more.
In 2026, investors weight gross-profit-adjusted payback and cohort trends over a single blended number. The 2026 Aleph × Benchmarkit benchmark report puts the median B2B SaaS CAC payback at 16 months, based on 198 of 342 participating companies reporting full-year 2025 actuals. The reporting artifact must be the investor-facing narrative that survives the room, not a dashboard build.
That artifact starts with structure. Most CAC payback period reporting for investors arrives as a single number on a slide, with no supporting rows, no prior-quarter comparison, and no plan variance. Investors cannot assess trend, methodology, or credibility from one figure.
Get A CRM-Connected Payback Audit
The Reporting Table Investors Expect For CAC Payback Period
Investors expect a structured quarterly comparison table that contrasts revenue-based and gross-profit-adjusted payback across key reporting elements and explains why each one matters. This format lets them test both the number and the logic behind it.
| Reporting Element | Revenue-Based Payback | Gross-Profit-Adjusted Payback | Why Investors Ask |
|---|---|---|---|
| Payback Period | Understated by 15–25% (see above) | Accurate cash recovery | Measures capital efficiency |
| CAC Definition | Often paid-only | Fully loaded: salaries, commissions, spend, onboarding | Tests S&M allocation discipline |
| Cohort View | Blended only | By cohort and segment | Screens for trend, not level |
| Churn Context | Absent | Paired with NRR and GRR | Tests whether payback survives |
Each row in the table answers a specific investor question. The payback period row is the headline figure, showing gross-profit-adjusted months to recovery. The CAC definition row tests whether the cost basis is complete. The cohort view row highlights trend instead of a single blended level. The churn context row tests whether payback holds once retention is applied.
This table is the investor and board-meeting narrative artifact, distinct from the operational reporting layer.
Gross-Profit-Adjusted Vs. Revenue-Based Payback: The Credibility Issue
Revenue-based payback is the most common reason a CAC payback number gets challenged in the room. As Ritik Namdev, Growth Marketing Manager at Fairview, states: “A 76% gross margin versus an 82% gross margin changes a reported 12-month payback to a 16-month payback. That single input can determine whether your go-to-market looks efficient or structurally challenged to an investor.”
The gross-profit-adjusted formula is: CAC ÷ (Monthly Gross Profit per Customer). Monthly Gross Profit per Customer equals MRR per new customer multiplied by gross margin percentage. Aleksandar Stojanovic, CEO and Founder at Fiscallion, estimates that 70%+ of founder-built CAC payback calculations use blended gross margin. A company at $13M ARR was reporting a 12-month payback on a 74% blended margin, but the corrected payback was 16.5 months once subscription-only gross margin of 64% was applied.
The adjustment is an investor-credibility requirement, not an accounting preference. The gross margin adjustment in CAC payback is non-negotiable: if gross margin is 75%, only 75 cents of every dollar of new revenue is available to repay CAC. Investors will recompute this number whether or not the presenter does.
For the full calculation methodology, see CAC Payback Period Calculation Methodology: A SaaS Guide. The same credibility standard applies to how you define CAC itself, which leads directly into the blended versus paid discussion.
Blended Vs. Paid CAC: How To Report Both Without Inviting The Objection
A blended CAC that includes organic and self-serve sign-ups can hide paid-channel inefficiency. If blended CAC and paid CAC differ by more than 2x, blended CAC should not be used in any conversation about scaling paid media. Investors raise this objection because they have seen healthy blended numbers hiding paid channels running at two to three times the blended figure.
The typical paid-to-blended CAC ratio for venture-backed SaaS is 2.4x to 3.1x, meaning roughly 60–70% of new customers arrive through organic search, brand direct, referral, product-led signup, community, or content. Present both numbers side by side, with the paid figure broken out by channel where the data supports it.
For CAC payback period in investor reporting, blended CAC belongs in cash-efficiency conversations. Paid CAC by channel belongs in the scaling conversation. Keeping them separate avoids the objection.
Cohort And Segment Breakdown: Why A Single Number Gets Challenged
A single blended CAC payback number gets challenged because it is a weighted average of past cohorts acquired under different conditions. Inflection CFO describes the cohort maturity trap: older sticky cohorts can mask deteriorating retention, expansion, and payback in newer cohorts. A company with 1,000 customers showed aggregate 14-month payback, but cohort-level data showed newer cohorts at 18-month payback with 2.1x LTV:CAC versus 3.6x for the aggregate.
Present payback by cohort and by segment such as SMB, mid-market, and enterprise. The Optifai Sales Ops Benchmark of 939 B2B SaaS companies (Q2 2025–Q1 2026) reports median CAC payback of 8–12 months for SMB under $15K ACV, 14–18 months for mid-market at $15K–$100K ACV, and 18–24 months for enterprise above $100K ACV. Applying an SMB benchmark to an enterprise motion, or blending the two, produces a number that neither segment can defend.
Investors screen for the derivative, not just the level. A move from 32 months to 24 months over two quarters is materially different from a flat 24 months. Cohort trends over time carry more weight than a point-in-time blended figure.
For benchmark context by ARR band, see CAC Payback Period Benchmarks For SaaS: Is It Normal?
Review Your Cohort-Level Payback
The Churn Trap: When A Strong Payback Number Is Undermined
A strong payback number collapses if customers churn before the payback window closes. A 15-month payback with 85% logo retention is a structural problem because some customers churn before recovery; the same 15-month payback with 96% retention is a deliberate investment strategy.
Pair CAC payback with net revenue retention and a retention curve so the payback figure is not read in isolation. Never present NRR to a board without GRR on the same slide. A company reporting 115% NRR alongside 78% GRR is masking serious core churn with expansion sales. Present both GRR and NRR alongside payback on every investor slide.
The Written Investor Narrative: Template For Improving And Worsening Trends
Most CAC payback period reporting for investors arrives as a number without a narrative. When the number worsens, presenters often avoid it or explain it defensively, which damages credibility. Founders who openly share challenges are 3.2x more likely to secure follow-on funding.
A short narrative paragraph for each trend follows a four-part structure: the number, the driver, the watch item, and the action.
For an improving trend: “CAC payback improved from [prior] to [current] months this quarter, driven by [specific driver, such as improved lead quality from ICP tightening or higher ACV from a packaging change]. We are watching [watch item, such as whether the improvement holds as we scale the mid-market segment]. The action in place is [specific action, such as channel-level payback review before any budget increase].”
For a worsening trend: “CAC payback extended from [prior] to [current] months this quarter, driven by [specific driver, such as ramping AE headcount or a channel mix shift toward enterprise]. NRR held at [X]% and the cohort retention curve shows [Y]% at month [Z], so the payback extension reflects a deliberate investment in [segment or motion] rather than a structural efficiency problem. The action in place is [specific action, such as a channel-level payback audit before Q[X] budget approval].”
Objection Handling: The Three Questions Investors Ask
Investors raise the same three objections when reviewing CAC payback. Presenters who cannot answer these concisely lose credibility on every other metric in the deck. The language below is designed for use in the room: concise, defensible, and free of methodology debate.
Objection 1 — Blended CAC Masking Channel Efficiency: “Paid CAC is X months, blended is Y. The gap reflects organic and self-serve contribution, which we report separately. For Series B B2B SaaS, no single channel whose paid CAC exceeds 2x the blended CAC figure is in our scaling plan without a standalone payback review.”
Objection 2 — S&M Allocation Flaws: “Fully loaded CAC includes SDR salaries, commissions, tools, and allocated marketing time. Here is the build-up.” Fiscallion documents a case where a CFO and a VP of Sales brought two different CAC figures, $18,400 and $11,200, for the same period to the same board meeting, neither wrong, because the definitions differed. The fix is a two-row table that writes out both definitions explicitly.
Objection 3 — The Churn Trap: “Payback is X months against a retention curve showing Y% at month X. NRR is Z%, GRR is W%. The payback figure is not read in isolation from the retention curve.”
For a full board reporting framework, see CAC Payback Reporting For Board: B2B SaaS Leaders.
Why This Reporting Requires CRM-Connected Measurement And Where SaaSHero Fits
A gross-profit-adjusted, cohort-level, blended-versus-paid CAC payback report cannot come from ad-platform conversion counts. It requires optimization and reporting against CRM revenue data: qualified pipeline, lifecycle stage, and closed revenue. An account optimized toward a form fill trains the bidding algorithm toward the wrong audience, and the CRM shows the damage only after the budget is spent.
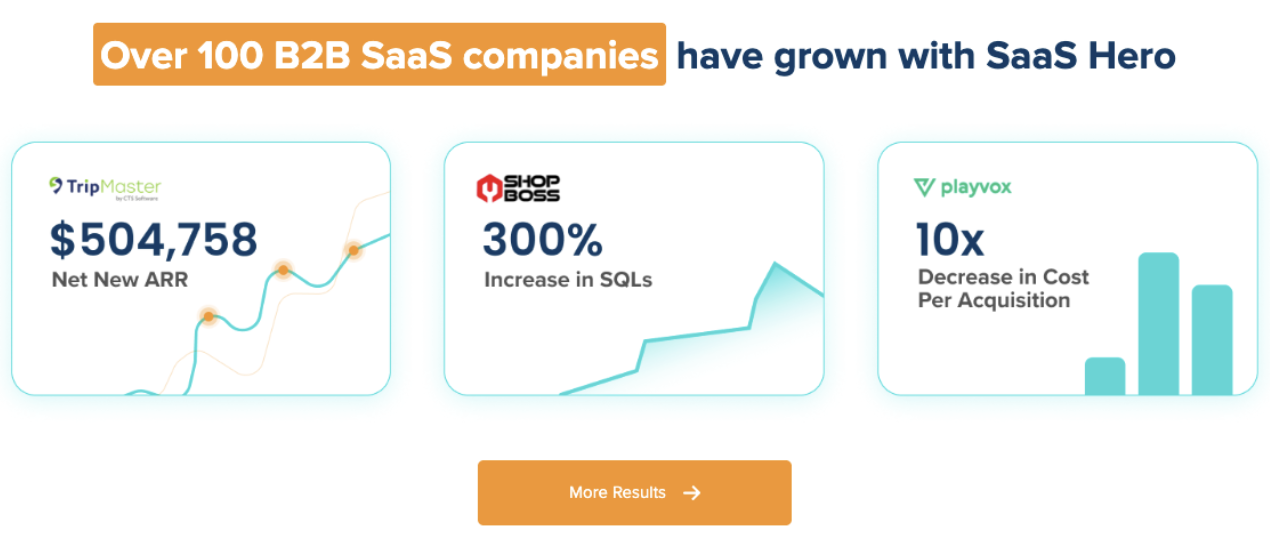
SaaSHero is the outsourced inbound growth team for B2B SaaS that owns paid media, creative, landing pages, and attribution and reporting as one team, optimizing against CRM outcomes rather than the conversion counts the ad platforms report back. That model has been running since 2018 across more than 100 B2B companies and roughly $16 million in annual advertising spend each year. The team is approximately 20 full-time in-house specialists, and the work has earned a Google Premier Partner designation, held by the top 3% of agencies, and a G2 High Performer ranking in digital marketing for over two consecutive years, currently #20 of approximately 6,000 agencies.
The benchmarks SaaSHero holds clients to are clear: LTV:CAC of 3:1 as generally healthy for SaaS, and CAC payback under 12 months as strong. Reporting runs on CRM-connected Looker Studio and HubSpot dashboards. Those dashboards show pipeline, CAC, and payback period, not impressions and clicks. For how CRM-connected measurement works in practice, see How To Calculate CAC Payback Period In HubSpot & Salesforce.
Build Your Investor-Ready Payback Report
Frequently Asked Questions
What Is Considered Good CAC Payback For Investors?
The answer depends on gross-margin adjustment, customer segment, and retention context, not just the headline month count. Under 12 months is strong and considered the gold standard for SMB-focused SaaS. Twelve to 18 months is sustainable for mid-market motions. The 18-month threshold mentioned earlier is especially relevant in tighter capital markets, where the median CAC payback across $5M–$50M ARR companies has stretched to approximately 17–18 months. The number must be gross-profit-adjusted to be comparable across companies or against any published benchmark. A 20-month payback with 130% NRR and an improving cohort trajectory is a materially different asset than a 20-month payback with 85% logo retention and a flat trend. Investors read the combination, not the number in isolation.
What Are The Downsides Of CAC Payback As An Investor Metric?
Two structural limitations apply. First, the churn trap: a short payback period means little if the customer churns before the window closes. A 6-month payback with 30% annual logo churn is not a healthy signal because a meaningful share of acquisition cost is never recovered. Second, the segment-expansion problem: low payback in an early adopter niche often deteriorates when scaling to broader, less-qualified segments, because the new cohorts carry higher CAC and lower retention than the historical average. A blended payback figure hides both problems. Cohort-level reporting is the only way to distinguish a genuinely efficient acquisition motion from one propped up by older, stickier customers acquired under different conditions.
What Is The Difference Between ROI And Payback Period?
ROI measures total return over the customer lifetime relative to acquisition cost. CAC payback period measures how many months it takes for gross profit to repay acquisition cost. A company can have a strong LTV:CAC ratio and a long payback period simultaneously. A 5:1 LTV:CAC with a 36-month payback can still starve a self-funded growth plan of cash because the return shows up too slowly to reinvest. Investors use payback as the capital-efficiency check and LTV:CAC as the long-horizon return check. Both belong in the investor reporting package, and payback has become the leading metric in the post-2022 environment because it depends on numbers already in the ledger, not on a lifetime estimate nobody can verify for a four-year-old company.
Why Doesn’t Discounted Payback Apply To SaaS CAC?
Discounted payback applies a cost of capital to future cash flows, which is a capital-budgeting framework. SaaS CAC payback is a cash-recovery timing metric, not a capital-budgeting metric. The relevant adjustment is gross margin, converting revenue into the cash actually available to repay acquisition spend, not a discount rate.
Applying a discount rate to SaaS payback introduces a lifetime assumption before the payback window has closed. A dollar of margin recovered later is worth less both for time value and for the risk the customer is gone by then. This lengthens payback materially, three to five months on a thirty-month enterprise curve in a high-rate environment, but is immaterial for short-payback SMB motions. The gross-margin adjustment is the correct and investor-standard adjustment. Discount rate adjustments belong in discounted payback period calculations and LTV modeling, not in simple (undiscounted) payback period reporting.
How Should A Worsening CAC Payback Trend Be Presented To Investors?
A worsening trend should be presented with the number, the driver, the retention context, and the action, never avoided and never left unexplained. Investors screen for the derivative. The derivative matters more than the level. As noted earlier, a move from 32 to 24 months is a positive signal even if the absolute number is above target. The narrative should state what caused the extension, such as ramping headcount, channel mix shift, or moving upmarket, what the retention curve shows alongside it, including NRR, GRR, and cohort payback at 12 months, and what specific action is already in motion. A worsening payback paired with improving NRR and a named corrective action is a defensible position. A worsening payback with no retention context and no action damages credibility on every other metric in the deck.
Conclusion: The Reporting Artifact That Survives The Room
Revenue-based, blended, point-in-time CAC payback period reporting for investors gets challenged in the room. The presenter who cannot defend the number loses credibility on every other metric in the deck. The reporting artifact that survives investor scrutiny is the quarterly comparison table with the rows investors expect, the gross-profit adjustment, the cohort and segment view, the written narrative for both improving and worsening trends, and the objection-handling script.
Start by auditing your current CAC payback calculation against the gross-profit-adjusted formula, because that adjustment determines whether the number is defensible at all. Once the formula is correct, build the quarterly comparison table so the number has the trend and variance context investors expect. Then confirm your measurement connects ad spend to CRM revenue. Without that connection, the table rests on ad-platform conversion counts rather than closed revenue, and the slide cannot be trusted.
Build Your Investor-Ready Payback Report