


Written by: Aaron Rovner, Founder, Saas Hero
Key Takeaways
- Series B investors evaluate marketing ROI through unit economics such as CAC payback, LTV:CAC, marketing-sourced versus influenced ARR, and cohort retention, not impressions or MQLs.
- Attribution alone shows correlation, while a three-layer proof that includes incrementality testing such as geo holdouts supports a causal claim.
- Blended CAC can mask poor cohort quality, so investors expect per-channel retention and expansion data to confirm customers stay and expand past payback.
- The diligence appendix wins or loses the argument by documenting spend definitions, attribution models, and sourced versus influenced ARR splits.
- SaaSHero serves as an outsourced inbound growth team for B2B SaaS and focuses on CRM revenue data rather than form-fill counts.
Talk With SaaSHero About Investor-Ready Reporting
What Metrics Do Series B Investors Actually Want To See?
Series B investors do not underwrite campaign metrics. They underwrite unit economics. The table below shows the five metrics that appear in diligence questions, data room requests, and partner-meeting follow-ups, and the specific investor question each metric answers. Read it as a map: every metric you present should respond directly to one of these questions.
| Metric | Formula | Investor Question It Answers |
|---|---|---|
| Customer Acquisition Cost (CAC) | Total sales and marketing spend (fully loaded, including personnel) ÷ new customers acquired in the same cohort period | “What does it actually cost you to acquire a customer, and what is in that number?” |
| CAC Payback Period | CAC ÷ (average MRR per customer × gross margin %) | “How long does it take to recover the cost of acquiring a customer?” |
| LTV:CAC Ratio | Gross-margin-adjusted LTV ÷ fully loaded CAC | “Is the business acquiring customers efficiently enough to justify scaling spend?” |
| Marketing-Sourced vs. Marketing-Influenced ARR | Sourced: closed ARR where first known touch is a marketing-owned channel. Influenced: closed ARR where any marketing touch occurred before the opportunity opened. | “How much of your revenue did marketing actually create versus touch?” |
| Cohort Retention and Expansion by Acquisition Channel | Net revenue retention per cohort, segmented by the channel that originated the customer | “Do the customers you acquire stay and expand, or churn before payback completes?” |
On CAC: a fully loaded CAC must include ad spend, agency fees, marketing and sales team salaries, CRM and marketing automation tooling, and content production. Excluding personnel costs, which typically represent 50–70% of total acquisition cost, is the most common reason a CAC number collapses under diligence questioning.
On benchmarks: the 2026 median CAC payback for Series B sales-led SaaS sits at 14 months, up from the 18-month median that OpenView’s 2022 SaaS Benchmarks Report found for one specific segment. These figures are historical context, not targets. Build a defensible baseline from your own cohort data rather than citing a dated median. The same logic applies to LTV:CAC. On LTV:CAC, the 2026 Aleph × Benchmarkit benchmarks define 3:1 as the minimum bar, 4–5x as healthy, and 7x+ as best-in-class for B2B SaaS, and they warn that computing LTV on revenue rather than gross profit is the most common way the ratio gets overstated.
Objection preempted: “Your CAC looks low, so what is excluded from that number?”
Marketing Attribution vs. Causation: The Three-Layer Proof
Those five metrics answer what investors want to see. A deeper question sits underneath every one of them, which is whether the numbers reflect correlation or causation. No ranking competitor covers this distinction as a first-class section, yet it is the most consequential gap in how marketing ROI is usually presented to investors and the one most likely to surface as a diligence question.
Attribution records which touchpoints appeared before a conversion, showing correlation. Incrementality compares an exposed group against a held-out control to estimate what a channel actually added beyond what would have happened anyway, showing causation. High-attribution channels like branded search frequently show low incremental lift.
The three-layer proof framework structures the investor conversation:
- Layer 1 — Attribution: What touched the deal. Multi-touch attribution across the full sales cycle, documented with a consistent methodology held for at least four quarters. Changing attribution models mid-process is a major way to destroy CFO trust, because the quarter a company switched from last-touch to multi-touch and marketing’s number jumped from 22% to 47% was the quarter it became unbelievable.
- Layer 2 — Cohorts: What happened to customers acquired through each channel over time. Retention, expansion, and LTV broken out by acquisition source, not blended. Series B diligence commonly expects retention curves by acquisition cohort, plus NRR and GRR broken out by ICP segment and ACV tier.
- Layer 3 — Incrementality: What would not have happened without the spend. The concrete methods are geo holdout tests and matched-market tests. In a geo holdout, a channel is paused in a defined geography for a defined period while a comparable control geography holds spend steady, and the resulting pipeline difference becomes a defensible causal claim. For B2B SaaS, pipeline creation is an acceptable primary metric when monthly closed-won volume is too low for statistical significance on revenue alone.
Attribution alone fails in B2B because modern buying committees average 6–10 people and sales cycles often extend beyond 200 days. Last-click attribution often credits the branded search that happened after the decision was already made. Layer 3 turns a correlation claim into a causal one.
What belongs on the slide: a one-line summary of the attribution methodology, the sourced versus influenced split, and whether an incrementality test has been run. What belongs in the diligence appendix: the full methodology documentation covered in the next section.
This three-layer proof requires CRM-connected measurement to function at all. The next section covers the methodology appendix that makes that measurement auditable.
Objection preempted: “Your attribution is just correlation.”
See How SaaSHero Builds Investor-Defensible Reporting
Cohort Quality: Why A Great Blended CAC Can Hide Churning Customers
Layer 2 of the three-layer proof, cohort analysis, deserves its own section because blended metrics often mislead here. A single blended CAC can look excellent while masking a channel that acquires customers who churn before payback completes. Investors want to see cohort-level LTV:CAC rather than blended averages, because a blended 3.5:1 can mask a deteriorating trend where early cohorts ran at 5:1 and the last three cohorts fell to 2:1.
The chain to present per channel runs in sequence: CAC, payback, retention, expansion, and LTV. Every efficiency metric must pair with a quality metric.
Consider two channels with identical CAC. Channel A produces customers who expand at month six and reach 130% NRR by month twelve. Channel B produces customers who churn at month nine, before payback completes. The blended CAC is identical. The business outcomes are not. This pattern shows up in aggregate retention numbers too. A blended 120% net retention is meaningless if older cohorts retain at 140% while newer cohorts retain at 90%, and Series B investors will find this in diligence anyway.
Objection preempted: “You are just buying growth.”
The Attribution Methodology Appendix: Where Diligence Is Won Or Lost
CAC changes dramatically with definitions, and investors will probe this. The appendix is where diligence is won or lost because it documents the choices that determine every number on the slide.
The appendix must document:
- What counts as marketing spend, whether ad spend only or fully loaded including personnel and tooling
- Whether salaries are included and how they are allocated between acquisition and retention
- Attribution model in use, such as first-touch, last-touch, or multi-touch, with the rationale
- How marketing-sourced and marketing-influenced ARR are defined and separated
- The attribution window, set against the high end of the actual deal-cycle distribution rather than a platform default
Multi-touch attribution is more accurate for long B2B sales cycles. It distributes credit across the touchpoints that actually moved the deal, instead of crediting only the last interaction. Last-click understates every upper-funnel channel and systematically defunds the demand creation that fills the pipeline months before a deal closes.
Objection preempted: “How did you calculate this, and would the number change if you calculated it differently?”
How To Build The Marketing ROI Slide For Your Series B Deck
With the appendix documented, the slide itself becomes a summary of decisions you can defend. Series B money funds the next dollar of spend. The slide must show how unit economics hold or improve as spend scales, plus a marginal-return forecast on the next dollar. A wall of platform metrics does not answer that question.
| Slide Element | What It Shows |
|---|---|
| The Five Numbers | Fully loaded CAC, CAC payback, LTV:CAC, marketing-sourced versus influenced ARR, and cohort retention, with one efficiency metric paired with one quality metric per channel |
| The Three-Layer Proof (one line) | Attribution methodology, sourced versus influenced split, and incrementality test status or plan |
| Cohort Quality Chart | Retention and expansion by acquisition channel, showing the CAC, payback, retention, expansion, and LTV chain per channel |
| Marginal-Return Forecast | Unit economics at current spend versus projected unit economics at 2–3x spend, with the narrative that every $1 of incremental marketing creates $X of gross profit |
The visual principle is simple: one efficiency metric paired with one quality metric per channel, instead of a wall of platform metrics. The narrative chain in plain language is that the marginal-return forecast directly answers what happens when you spend more.
Objection preempted: “What happens to these economics when you scale spend?”
What Are Common Marketing ROI Mistakes That Kill Diligence?
These mistakes are specific presentation choices that cause investors to discount or challenge marketing spend during Series B diligence.
- Leading with vanity metrics (impressions, clicks, MQLs) → Lead with pipeline created and CAC payback period instead. This mistake signals that marketing optimizes for volume rather than revenue.
- Presenting a single blended CAC → Show CAC by channel with cohort quality paired to each. This mistake hides deteriorating cohort quality behind an average.
- Reporting ROAS without margin → Report contribution margin, not gross revenue. Using gross-revenue LTV instead of gross-margin-adjusted LTV overstates the LTV:CAC ratio by 1.5–3x depending on margin structure. This mistake overstates the true return on ad spend.
- Showing large pipeline without conversion rates → Pair pipeline with stage conversion rates from MQL to SQL to opportunity to close. This mistake hides whether the pipeline can realistically convert to revenue.
Objection preempted: “These numbers look cherry-picked.”
Frequently Asked Questions
What Is The Difference Between Marketing-Sourced And Marketing-Influenced ARR?
Marketing-sourced ARR counts only closed revenue where the first known touch was a marketing-owned channel such as a paid ad click, organic search visit, or content download that opened the relationship before any sales contact. Marketing-influenced ARR counts closed revenue where marketing touched the account at any point during the buying cycle, including deals that sales opened through outbound. Influenced ARR is typically 2–4x higher than sourced ARR. Both numbers belong in the deck, labeled clearly, because they answer different questions: sourced shows origination credit, and influenced shows marketing’s reach across the full funnel.
How Do You Measure Cohort Retention By Acquisition Channel?
Cohort retention by acquisition channel requires a CRM field that captures the originating channel at the point of lead creation and follows that attribution through to closed-won and beyond. From there, net revenue retention is calculated on a fixed cohort, meaning customers acquired through a given channel in a given period, by measuring starting MRR, expansion, contraction, and churn over the trailing 12 months. The result shows whether customers acquired through paid search, paid social, or organic retain and expand differently, which provides the quality signal investors use to evaluate whether growth is durable.
What Is Incrementality Testing With A Geo Holdout?
A geo holdout test pauses a marketing channel in a defined set of geographic markets while holding spend steady in a matched control set. After a test window of typically four to eight weeks, the pipeline or revenue difference between test and control markets is measured as the channel’s true incremental contribution, meaning what would not have happened without the spend. For B2B SaaS with low monthly closed-won volume, pipeline creation is an acceptable primary metric. The result is a defensible causal claim rather than a correlation, which is what separates an incrementality test from an attribution model.
How Does Marketing ROI Differ From Unit Economics?
Marketing ROI is a campaign-level metric, calculated as net profit from a marketing activity divided by its cost. Unit economics are business-level metrics that describe the relationship between the cost of acquiring a customer (CAC), the revenue that customer generates over their lifetime (LTV), and how quickly the acquisition cost is recovered (CAC payback period). Series B investors underwrite unit economics rather than campaign ROI. A campaign can show strong ROI while the underlying unit economics deteriorate, for example when customers acquired through that campaign churn before payback completes. Translating campaign data into unit economics is the core task of investor-facing marketing reporting.
Conclusion: Building An Investor-Defensible Marketing Engine
The workflow that produces investor-defensible marketing numbers follows a clear sequence:
- Establish the baseline metrics.
- Demonstrate efficiency with fully loaded CAC and LTV:CAC.
- Prove quality through cohort retention by channel.
- Validate causation through incrementality testing.
- Build the slide.
- Document the methodology in the appendix.
SaaSHero is the outsourced inbound growth team for B2B SaaS built to own this entire chain. One team covers paid media, creative, landing pages and CRO, attribution and reporting, and strategy, and it focuses on CRM outcomes such as qualified pipeline, lifecycle stage, and closed revenue rather than the conversion counts ad platforms report back. The specific mechanism that makes investor-defensible numbers possible is the CRM-connected measurement layer described earlier, the one that separates primary from secondary conversions and pushes lifecycle events back into the ad platforms.
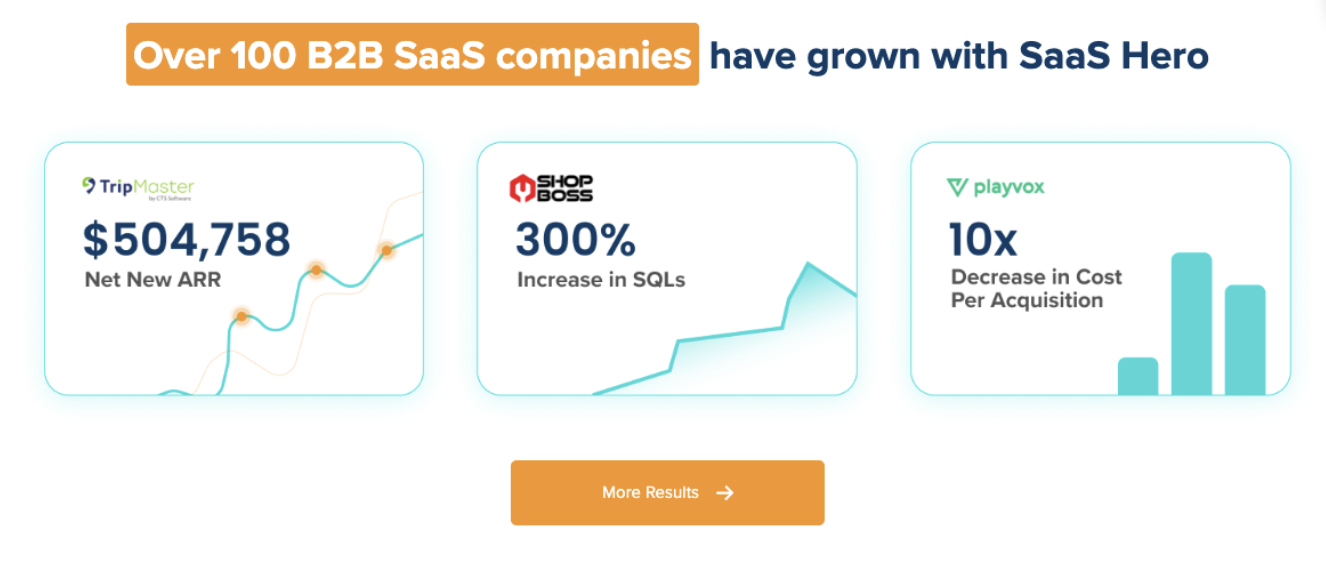
Founded in 2018, SaaSHero has served 100+ B2B companies, manages roughly $16M in annual ad spend ($60M+ lifetime), holds Google Premier Partner status (top 3% of agencies), and is ranked #20 of approximately 6,000 agencies as a G2 High Performer in digital marketing for two consecutive years. The team includes approximately 20 full-time specialists with in-house designers and copywriters.
SaaSHero works with B2B SaaS and professional services companies at $10M+ annual revenue and $15k+ monthly ad spend with an internal marketing team of 2–4 people and no paid-media specialist. That profile matches companies preparing for or navigating a Series B process. If that describes your situation, the next step is a discovery call.
Schedule A Discovery Call With SaaSHero